You miss a payment, then the options appear
The first missed payment usually doesn’t feel like a “choice” yet. It feels like a timing problem: paycheck late, hours cut, medical bill, rent jumping. Then the servicer notices. A past-due notice hits your inbox, autopay gets interrupted, and suddenly there’s a menu of fixes—some of them sounding like a clean pause, others sounding like a penalty.
This is the moment where deferment and forbearance show up as the two fastest levers. The pressure is that the clock is still running: late fees may appear on private loans, credit reporting can become a risk if the delinquency stretches, and federal loans can slide toward default if you do nothing. So the real task becomes choosing a “pause” that buys time without quietly inflating what you’ll owe later.
Side-by-side: what deferment and forbearance really do
Once you’re staring at those two buttons, the wording makes them sound like twins. In practice, deferment is closer to “I qualify for a defined reason,” while forbearance is closer to “I need breathing room right now.” The friction is timing: deferments can require documentation and a specific category (like school enrollment or certain hardships), while forbearances are often granted faster, sometimes with less paperwork, but with fewer built-in protections.
The real separation shows up in what happens while you’re not paying. With many federal deferments, some loan types stop charging interest for the period, which can keep the balance from creeping up. Forbearance usually means interest keeps accruing across the board, even if payments are set to zero. On private loans, both terms can exist, but the lender’s version often behaves like forbearance: short pause, interest running, and a clock that doesn’t stop just because cash flow did.
The balance question: when interest keeps running
After the first relief of getting a pause approved, the balance starts to matter in a way it didn’t when the problem was just “make this month’s payment.” If interest is still accruing, the loan is getting more expensive every day you’re not paying, even though your required payment is temporarily zero. That’s the part borrowers often don’t feel until they log in a month later and see the payoff amount has ticked up.
The key detail is what kind of loan you have and what kind of pause you’re using. When interest is subsidized during a qualifying federal deferment, the principal can sit still. When it’s not subsidized—most forbearances, and many deferments for unsubsidized or PLUS loans—interest keeps piling up in the background. Even if it doesn’t capitalize right away, it becomes a separate bucket you’ll either pay off later or carry into repayment, raising the total cost.
A practical way to compare options is to ask for the daily interest amount and multiply by the number of months you expect to pause. If that number feels like another bill you can’t afford later, a shorter pause, partial payments toward interest, or a different program may be the less damaging “breathing room.”
Capitalization: how a pause can raise your principal later
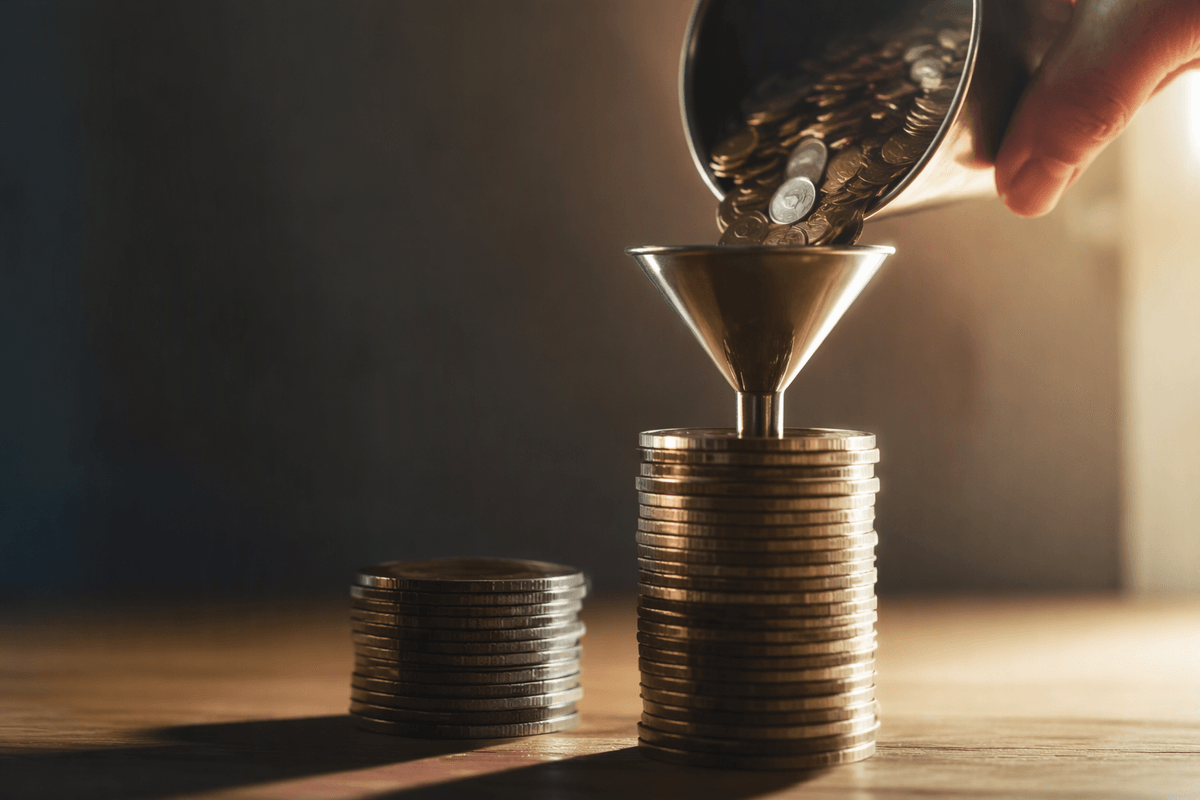
Then comes the part that feels like a technicality until it changes your future payments: capitalization. During the pause, interest can accrue in its own bucket, separate from your principal. Capitalization is when that unpaid interest gets added onto the principal balance, so the loan starts charging interest on a larger number. That’s why two borrowers can take the same three-month break, see similar accrued interest, and still end up with different long-run costs depending on whether and when capitalization is triggered.
The constraint is timing. Some pauses don’t capitalize interest until a specific event—when the deferment or forbearance ends, when you leave a qualifying status, or when you change repayment plans—while others can capitalize more routinely. Once it capitalizes, the monthly payment can jump because amortization now has to cover a higher principal. If you can scrape together anything during the pause, targeting the accruing interest (even irregularly) can keep that capitalization bomb smaller, especially on unsubsidized federal loans and most private-loan pauses.
Eligibility reality check: which pause you can actually get
By the time capitalization is on your radar, the next snag is that the “best” pause may not be available on demand. The servicer might offer forbearance in minutes, while a deferment request sits pending because it needs a form, dates, or proof that matches a narrow box. That gap matters when the payment due date is close and you’re trying to prevent a second missed payment.
In federal-land, deferment tends to be tied to a status you can document: in-school, certain unemployment or economic hardship situations, active-duty service, or specific programs. Forbearance is usually the catch-all when you don’t meet a deferment category or you need relief faster, but it often comes with interest running. A simple screening question helps: “Can I show I qualify for a named reason, right now?” If not, assume forbearance is what you’ll actually be offered, then decide whether you want to shorten the pause or pay interest during it to limit the damage.
Private loans: the same words, different rules
When the loan is private, the labels start to lose their predictability. A lender may offer “deferment” for in-school status, residency, or a short unemployment window, but the fine print often looks like a standard pause: payments stop, interest does not. Some contracts also tack on a servicing fee or require you to reapply every 30 days, which turns “relief” into a monthly admin chore right when bandwidth is low.
The practical move is to treat every private-loan pause as an interest-and-capitalization negotiation. Ask what happens to unpaid interest during the pause, what event triggers capitalization, and whether they’ll accept interest-only payments while the required payment is set to zero. Then check the other constraint people miss: whether the paused months still count against the total term, because a pause that doesn’t extend the schedule can force higher payments later.
Choosing under pressure: minimize damage while buying time
At this point, the “right” choice is usually the one that keeps you current fastest and limits how much the balance can quietly grow. If a qualifying federal deferment would subsidize interest on any of your loans, that’s the rare pause that can buy time without adding cost. If you’re being steered to forbearance (or a private-lender pause), treat it like borrowing extra money at your current rate, day by day.
Under deadline pressure, a simple playbook helps: get the pause approved before the due date, confirm the capitalization trigger in writing, and set a calendar reminder for the end date. Then decide if you can cover interest-only payments during the pause; even small, uneven payments can prevent a bigger principal jump later. The goal shifts from “pause everything” to “pause the required payment, keep the damage contained.”