You’re excited—then the clawback paragraph appears
The offer email lands and the numbers look clean: base, bonus, maybe relocation, maybe a paid certification. Then there’s the paragraph that changes the emotional math—repayment if you leave “for any reason” within a window that’s longer than you expected. It’s usually one dense block of legal language, and it arrives right when you’re already picturing the new commute and the first paycheck. The friction is timing: you’re being asked to commit before you’ve modeled what happens if the job is a mismatch or the team shifts six months in.
What makes it slippery isn’t the existence of a clawback; it’s the missing edges. Is the clock 12 months or 24, and does it start on your start date or your payment date? Is repayment prorated or all‑or‑nothing? Does “leave” include layoffs, internal transfers, or termination without cause? And if the bonus hit your account net of withholding, are they expecting the gross amount back anyway? Until those answers are explicit, the “bonus” is less cash and more a short-term loan with conditions.
What you assumed the bonus meant versus reality
In your head, a signing or relocation bonus behaves like salary: it’s part of the deal, you do the work, you keep the money. The offer language quietly flips that. The cash arrives up front, but the “earning” happens over time, and the company keeps the right to re-price the package if you don’t stay long enough. That gap matters because the first months of a new role are when uncertainty is highest—fit, manager dynamics, reorg risk—yet the repayment obligation is usually most expensive then.
The other assumption is that the downside is limited to what you personally chose. Many clauses don’t draw that line. “For any reason” can read like it includes a layoff, a role elimination, or a termination that isn’t misconduct. And even when repayment is prorated, the schedule may be slower than you expect (12 months of “service” but 24 months of “repayment”). Practically, it turns the bonus into conditional liquidity: helpful for a deposit or movers, but potentially a bill that shows up exactly when a job change has already disrupted cash flow.
Name the clawback structure you’re being offered
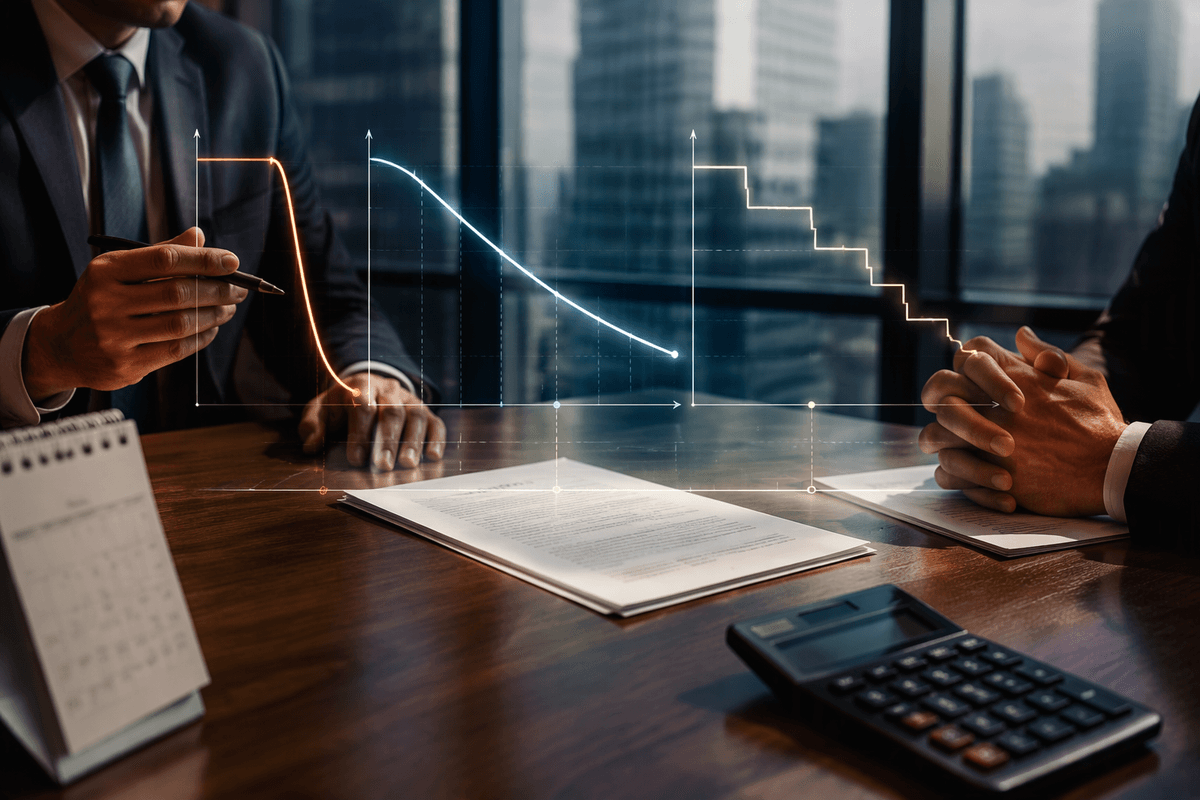
Before you start negotiating numbers, label what you’re actually looking at, because different clawbacks behave differently under stress. The simplest is a straight “signing bonus repayment” that’s either all-or-nothing inside a window (leave at month 11, repay 100%) or prorated on a schedule (often monthly or quarterly). A close cousin is tiered forgiveness: 100% if you exit before 6 months, 50% before 12, then zero—easy to read, but it can create a hard timing cliff if you’re already uneasy at month five.
Relocation and training clauses tend to be messier. Some are “fixed amount” repayment (a stated dollar figure regardless of what was spent), while others are “actual cost” reimbursement tied to invoices, which can balloon if the company used premium vendors. Sometimes it’s packaged as a promissory note with a payroll-deduction permission, which changes the collection mechanics and can compress your cash-flow timeline. Once you can name the structure, you can ask the right questions: what starts the clock, what events trigger repayment, and whether forgiveness is truly prorated or just feels like it.
Run three exit scenarios before you accept
Once you’ve labeled the structure, the next step is treating it like a small risk model, not a paragraph to skim. Pull out a calendar and write three dates you could realistically be gone: an early “this is a mismatch” exit (around 90 days), a mid-year exit (around 6 months), and a later exit (around 13–15 months). Those points usually line up with probationary periods, bonus cycles, or the moment a reorg becomes real. The constraint is timing: the clawback balance can be highest exactly when you have the least savings built back up after a move.
For each date, calculate what you’d owe under the actual language, not what seems fair. If it’s all-or-nothing, treat the full amount as due until the day the window ends. If it’s prorated, confirm whether it’s monthly, quarterly, or “per completed year,” because that one word changes the curve. Then stress it: assume you leave without another job lined up and you’re also paying for overlap costs (temporary housing, double rent, or a short gap in health coverage). If the “month 6” scenario creates a bill you couldn’t cover within 30 days, you’re not evaluating a bonus anymore—you’re accepting a cash-flow obligation with a countdown.
Taxes, withholding, and why repayment can sting
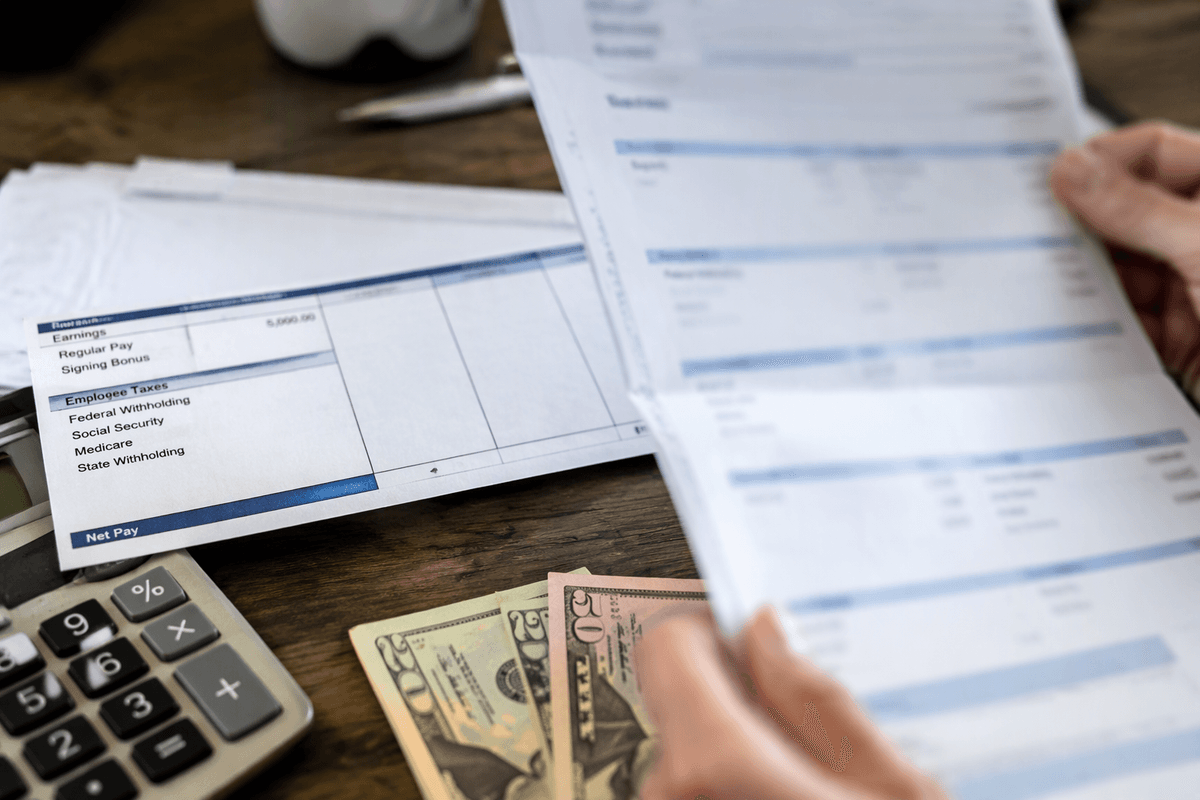
The part that tends to surprise people isn’t the repayment clause itself, it’s how the money moved through payroll before it ever hit your account. A signing bonus is usually paid as wages, which means withholding comes out immediately. So if the offer says “repay $10,000” and you only received, say, $6,500 after federal, state, and payroll taxes, the practical constraint shows up fast: the company can ask for the gross amount back, not the net you actually have.
Even when the employer agrees to take back only what you received, taxes rarely unwind cleanly on your schedule. If repayment happens in a different tax year, you may be chasing a deduction or a credit rather than getting your withholding back as cash. That turns into a timing problem, not an accounting problem: the repayment is due now, while any tax benefit may arrive months later when you file, and it may not match dollar-for-dollar. In cash-flow terms, the clawback can feel larger than the “bonus” ever felt.
Get clarity in writing without sounding adversarial
At this point the numbers are less mysterious than the missing mechanics, and that’s the easiest place to get specific without turning it into a fight. A short email that frames it as “I’m aligning my understanding before I sign” usually lands better than “I need this changed.” The constraint is speed: offers often come with a 48–72 hour decision window, so you’re trying to reduce ambiguity quickly, not litigate edge cases for a week.
Ask for a written confirmation (or redlined sentence) on four items: what date starts the clock, which separations trigger repayment (voluntary resignation versus layoff/termination without cause), whether repayment is prorated and on what schedule, and whether repayment is gross or net of withholding. If there’s payroll deduction language, ask how it works if your final paycheck is smaller than the balance. The tone that keeps it non-adversarial is consistency: “I want to be sure I can plan cash flow if something unexpected happens,” not “I don’t trust this.”
Decide: accept, negotiate, or treat it as debt
By now you usually feel a shift: the clause stops being “legal fine print” and starts behaving like a financing term. If the balance at your 90‑day or 6‑month scenario is survivable and the triggers are narrow (ideally excluding layoff/termination without cause), accepting can be rational—just ring‑fence the money in a separate account until the window burns off. The constraint is emotional: it’s hard to leave cash untouched when the move already strained your budget.
If the language is broad, the proration is slow, or repayment is clearly gross, negotiate as a risk trade, not a favor. Ask for faster forgiveness, a smaller amount, or a company‑initiated separation carve‑out. When they won’t move, treat it as debt: assume you’ll owe it, price it into your decision, and compare offers on after‑repayment downside. That framing usually clarifies what you’re actually comfortable carrying into month six.