Your “safe” CD suddenly needs an exit
The money looked settled until an ordinary expense changed the plan. A car repair, a job transition, or a better savings opportunity can turn a fixed-term deposit into cash that suddenly matters today. The account still feels safe, but access now has a price, and that price may not match the attractive rate shown when the CD was opened.
Early withdrawal penalties are usually tied to interest, often measured in months rather than a flat fee. That makes timing important: leaving near the beginning of the term can consume more of the earned return, while withdrawing principal may create a larger loss than expected. Before treating one CD as the safer choice, the penalty formula deserves the same attention as its APY.
Compare penalty formulas before chasing the highest APY
Two CDs can advertise nearly identical APYs and still create very different exit costs. One institution may charge three months of simple interest, while another may take six months or apply the penalty to the amount withdrawn. A longer penalty period matters most when the account is closed early, before enough interest has accumulated to absorb the charge.
That makes the advertised yield an incomplete comparison. A 5.00% APY may produce less usable value than a 4.75% CD with a lighter penalty, especially if the money might be needed within the first year. Check whether the penalty is based on the original principal, the amount withdrawn, or interest earned, and whether the bank can take the difference from your principal. Timing also matters: some formulas use the CD’s current rate, while others use the contracted rate. The highest APY deserves attention only after the withdrawal formula is clear.
A short CD can cost less than expected
A shorter term can reduce the damage when cash needs change, even if its rate looks less impressive. A six-month CD with a three-month interest penalty may limit the cost of leaving early, while a five-year CD charging six months of interest can consume far more of the return. That difference becomes meaningful when the account is closed after only a few weeks, before enough interest has accumulated to cover the charge.
The trade-off is that short CDs often offer less time to benefit from a strong rate, and renewing them later may expose the deposit to lower rates or an inconvenient maturity date. A $10,000 deposit earning 4.50% for six months produces roughly $225 before compounding, so a penalty of three months’ interest could absorb about $112.50 if the full balance is withdrawn. A longer CD might earn more over time, but its larger penalty and longer commitment can create a higher access cost. The cheaper choice depends on how likely the money is to stay untouched, not just on the term’s advertised APY.
The fine print changes the withdrawal math
The quoted penalty may still leave out the detail that determines the actual loss. Some banks calculate interest daily, while others use the rate stated in the account agreement and round the charge in ways that make a small withdrawal less efficient. A partial withdrawal may be unavailable altogether, forcing the entire CD to be closed. That can turn a manageable cash need into a full early-exit decision.
Check what happens to interest already paid. The institution may reclaim it from the account, deduct the penalty from remaining interest, or take the shortfall from principal if the earned interest is not enough. A CD opened with monthly interest payments can therefore create an unexpected balance reduction when closed early. The grace period at maturity matters too: withdrawing or changing the account during that brief window may avoid a penalty, but missing it could trigger automatic renewal. These details are easy to overlook because the APY receives the attention, while the account agreement controls the money that actually comes back. A lower-rate CD with partial withdrawals or a clearer grace period may be more useful than a higher-rate account with rigid access rules.
When rates rise, the cheapest exit may differ
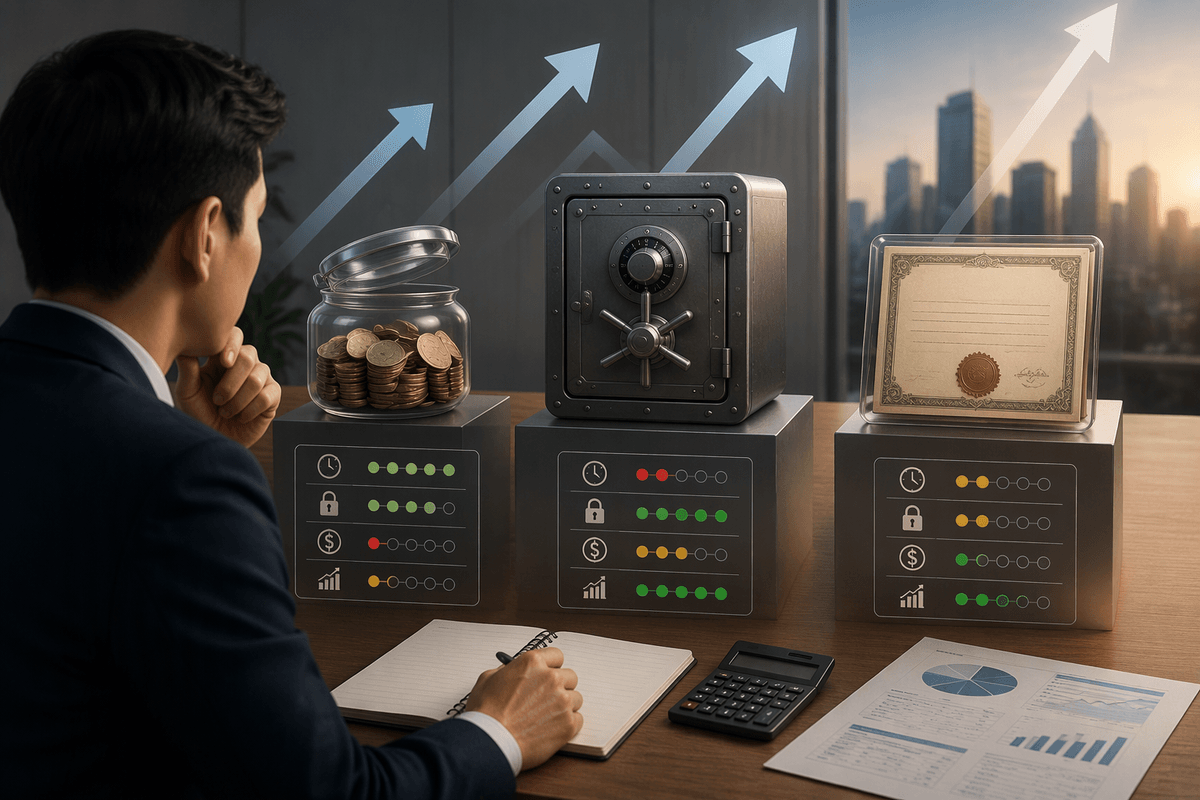
A rising-rate environment can change the least expensive exit even when the penalty formula stays the same. Suppose a $10,000 CD earns 4.50%, but similar accounts begin offering 5.25% before maturity. Breaking the original CD may cost three months of interest, or roughly $112.50, while keeping it means giving up the higher rate for the remaining term. If only a few months remain, switching may not recover that penalty. If a year remains, the rate difference has more time to offset it.
The calculation also depends on where the replacement money goes. Moving into a liquid savings account may provide access but earn less than another CD, while opening a new long-term CD can recreate the same restriction. A penalty-free withdrawal feature, if available, may make the original account more valuable than its lower APY suggests. Compare the one-time exit charge with the extra interest available over the period the replacement account would actually be held. A higher rate is not automatically a better escape route; the cheapest choice may be staying put until maturity, especially when the remaining balance is small or the rate gap is narrow.
Estimate the penalty using your own deposit
Once the rate difference is clear, run the penalty against the balance actually at risk. For a $12,000 CD earning 4.80% with a six-month interest penalty, the estimated charge is $288: $12,000 × 0.048 × 0.5. If the account has earned only $140 so far, the institution may take that interest and deduct the remaining $148 from principal, depending on the agreement.
Repeat the calculation using the amount you might withdraw, the contracted rate, and the stated penalty period. Then compare that cost with the extra interest from moving the money elsewhere. A spreadsheet can expose differences that a headline APY hides, but the estimate remains incomplete until taxes, lost future interest, and any limits on partial withdrawals are included. Even a rough personal calculation narrows the decision: the best CD is not necessarily the one with the highest return, but the one whose likely exit cost remains tolerable.
Choose the CD whose restrictions fit your life
The final choice should reflect how the money is likely to behave, not just how long the CD promises to pay. Funds reserved for a known date may fit a longer term and stricter penalty, while emergency savings usually need a liquid account, a short CD, or a penalty-free option. Accepting a higher APY makes less sense when a routine expense could force an early closure.
Before depositing, compare the penalty period, partial-withdrawal rules, grace period, and whether principal can be reduced. Then test the account against a realistic setback, such as needing half the balance three months early. A slightly lower yield may be the stronger choice if its restrictions prevent a costly mistake. The best CD is the one whose access limits remain manageable when life does not follow the original plan.